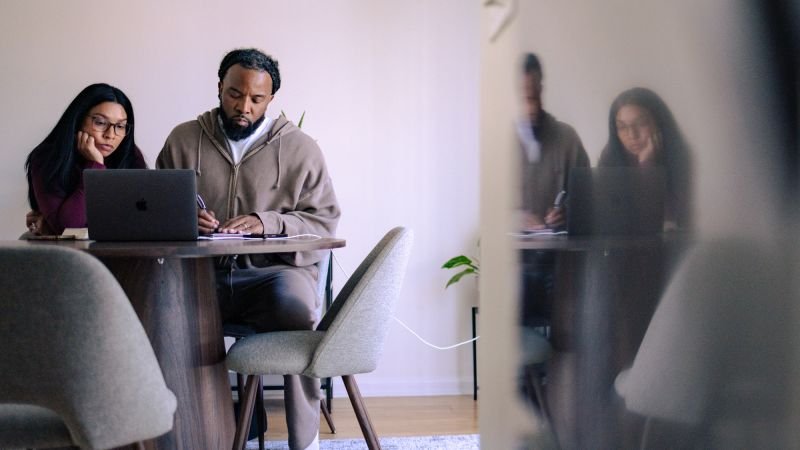
EDITOR’S NOTE: Mariza and Geffrey Gordon are among a handful of participants selected to work one-on-one with a financial expert for CNN’s Savings Challenge. This story was originally featured in the Savings Challenge newsletter, which you can sign up for here.
The last time CNN checked in with Mariza and Geffrey Gordon, the Milwaukee-based couple weighed down by debt who hoped to build an emergency fund and stop living paycheck to paycheck, they’d just gotten disappointing news.
They’d been told because of their credit scores, they didn’t qualify for a balance transfer card, which would have given them up to 21 months to pay off their nearly $40,000 in credit card debt interest free. Nor did they qualify for a personal loan at a lower rate to pay off what they owe. And the terms they were offered on a debt management plan just weren’t feasible for them.
A month later, though, the couple’s circumstances had changed: They received a modest inheritance from a relative – a big chunk of which they used to pay off their credit card debts. That freed up the roughly $1,400 a month they had been spending to make their minimum required payments.
While that has been a huge weight off their shoulders, it didn’t erase their need to rethink how they manage money so that they no longer just get by.
Nor did it erase the fact that Mariza’s two months of severance from her former job were about to run out. With her upcoming unemployment benefits, their monthly household income would be about $2,000 lower than it was when she was working. Plus, she still had to arrange for health insurance coverage, since they’d missed a deadline to add her to her husband’s employer plan.
When the couple shared news of their inheritance with Tiffany Aliche, the financial educator they’ve been working with, she advised them to come up with a plan before doing anything. But they emailed her soon after to say they used a large piece of it to clear their credit card debts.
While that wasn’t a bad decision, Tiffany said, she would have preferred they’d first taken a beat to consider how much money to set aside to cover them until Mariza finds a new job.
Tiffany said she might have suggested only paying off half their credit card debt, thereby improving their credit scores enough to qualify for a 0% interest balance transfer card, and then letting the rest of their money earn 4% in an online high-yield savings account until their financial circumstances stabilize.
Nevertheless, Tiffany said, “They were excited about doing the responsible thing. They did what they thought was right.”
But now she wants to work with them to interrupt their money patterns and have them think more holistically about their full financial picture. “I’m trying to reframe for them. Let’s disrupt your pattern and come up with a new [one] that can work for you,” she said.
While the couple left Tiffany with the impression that they’d already spent some of their remaining inheritance to help both Mariza’s sons buy cars and to make some home improvements, in fact, they’d only given one son $5,000 already. They put the remainder of their inheritance in a high-yield savings account, they told CNN.
And, Geffrey added, he is going to aim to save 20% of his paycheck every month. He said he already set up direct deposits into two new high-yield savings accounts, one of which had a 4% annual percentage yield.
What’s next: We’ll follow up with Mariza and Geffrey in a few weeks. But next week, Jeff Kizer learns about the debt pay-down strategy that may get him to a comfortable retirement at age 75.
JOIN CNN’S SAVINGS CHALLENGE
- Sign up here for CNN’s nine-week Savings Challenge. CNN’s Jeanne Sahadi delivers a newsletter every Friday with savings tips, expert answers to your questions and challenges to help you get your savings on track.

Responses